Tag: returns

Lumpsum vs. Dollar Cost Averaging (SIP)

Among Indian investors, SIPs (Systematic Investment Plans) are the rage right now. The total amount collected through SIP during May 2018 was ₹7,304 crore according to AMFI. SIPs are great for investors with a regular income – it matches the frequency of savings with the frequency of income. Structural discipline is always a welcome thing. However, for investors who have lumpy incomes or a windfall, it is often a dilemma whether to invest as a lumpsum or to setup an STP (Systematic Transfer Plan.)

Both SIPs and STPs are a form of DCA (Dollar Cost Averaging) where you average into an investment over a period of time (the accumulation phase.) The thing about DCA is that it ends up under-performing a lumpsum in markets that are trending up. Intuitively, you want to buy more when the price is low (in the beginning) and less when the price is high (at the end.) So, if the market is going up, then it makes no sense to spread a lumpsum over a period of time – you are guaranteed to make the later buys at a higher level, reducing your overall returns.

In the case of equity markets, the expectation is that they tend to go up over time. So if you are looking at a 10-20 year time horizon, then you are better off investing in one shot. To put this intuition to test, we modeled the returns of NIFTY, MIDCAP and GOLD as a Generalised Lambda Distribution (this works better than a normal distribution because these returns have significant skews and kurtosis) and ran a 10,000 path simulation to get a sense of the probability distribution of DCA vs lumpsum investments.

Roughly, this is like assuming that the weekly return distribution is going to be the same across 10,000 different worlds. So you pick set of random weekly returns from the same distribution 10,000 different times and see how DCA and lumpsum perform over those worlds. When you plot the density of those returns, you get an idea of how they compare.

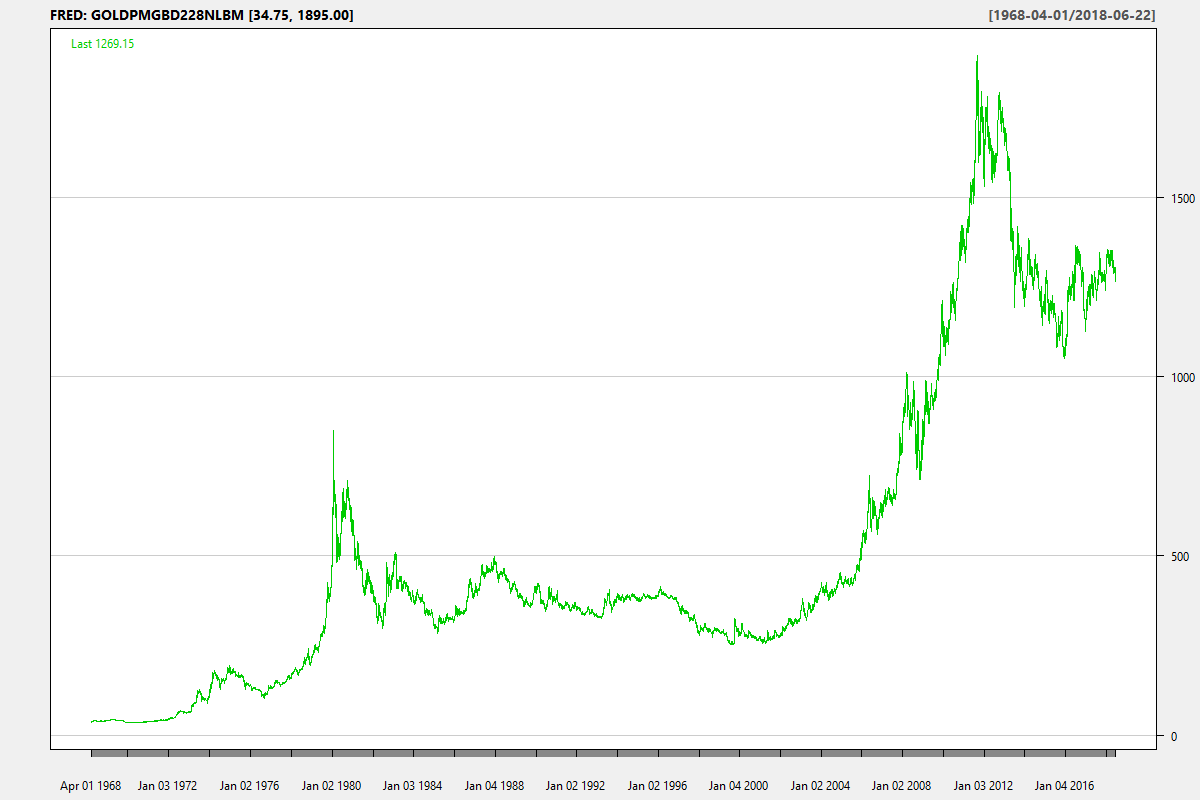
To keep things simple, lets compare NIFTY MIDCAP 100 and GOLD. First, the price charts:
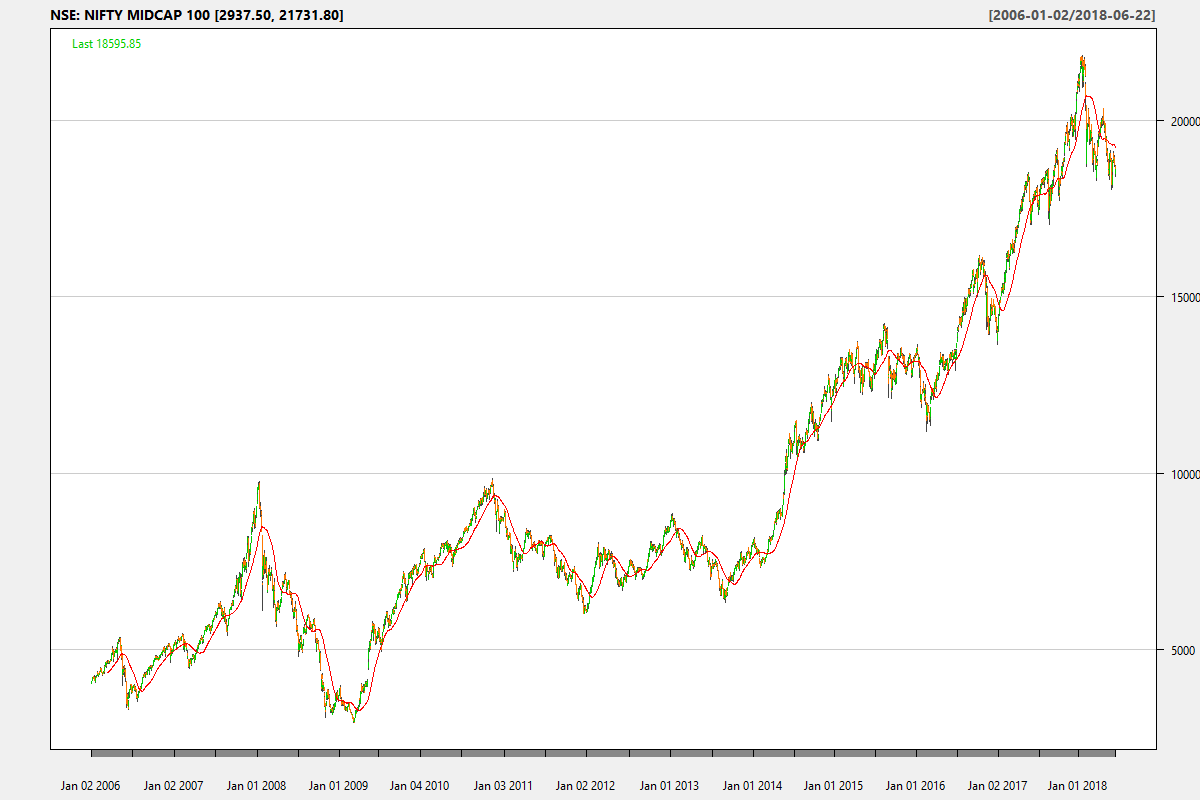
And now the simlulated cumulative return densities of MIDCAP and GOLD, modeled with data after 2010:
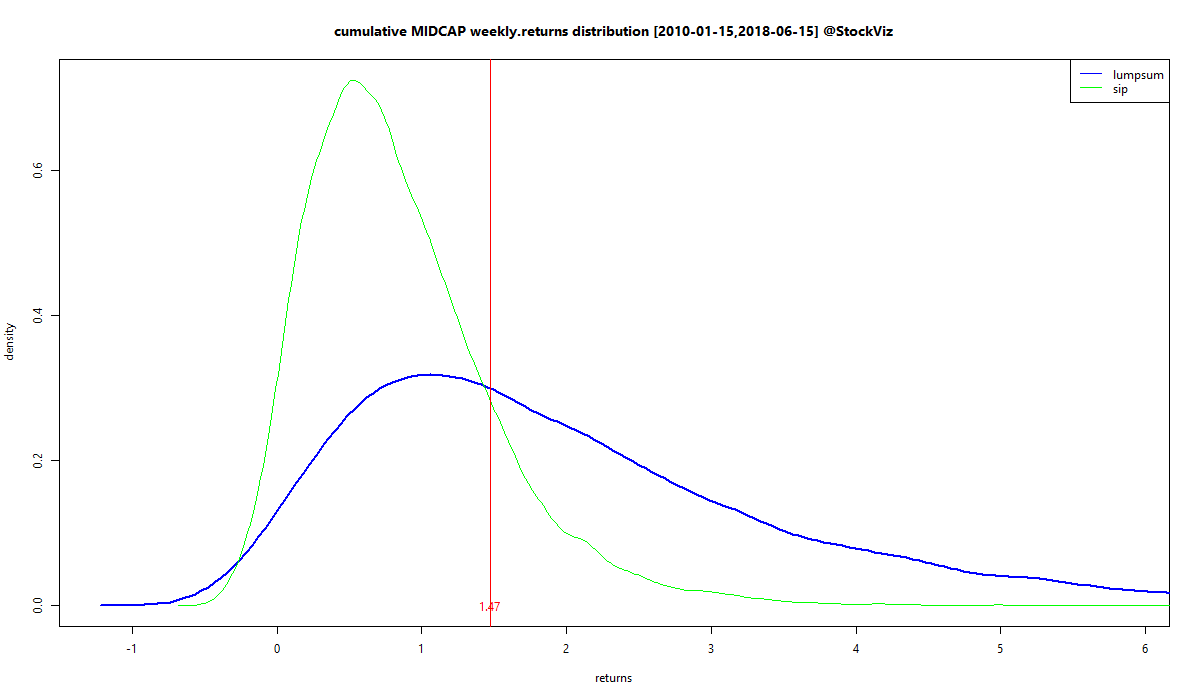
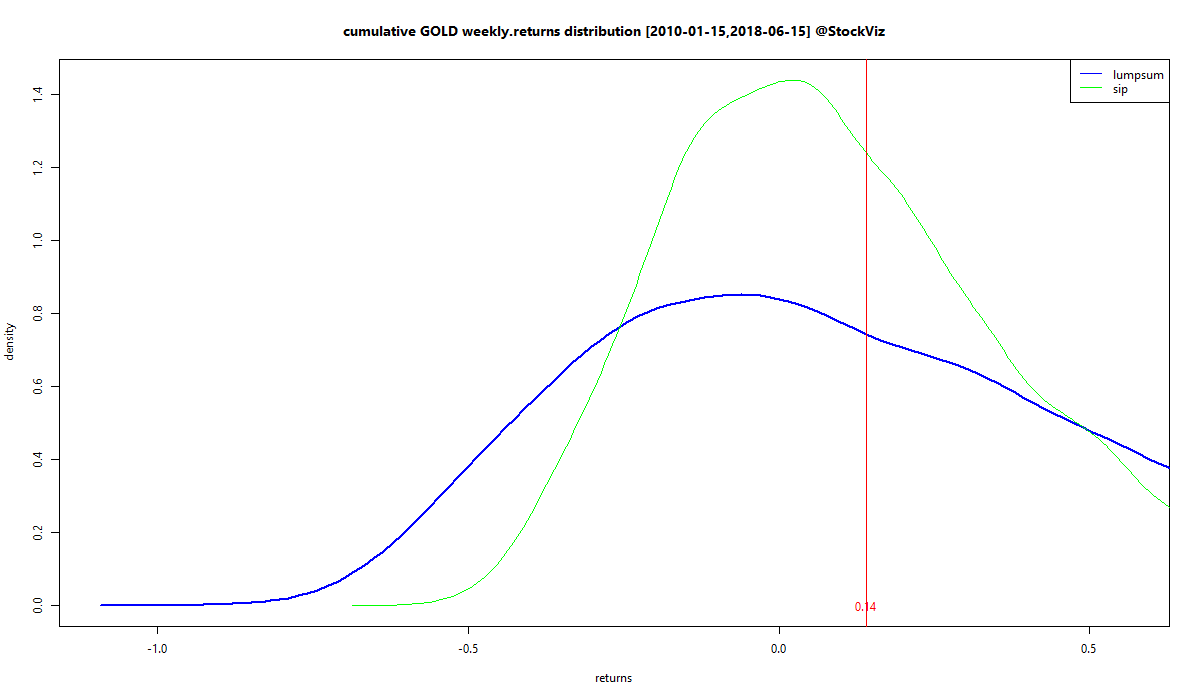
The area to the left of zero is that of negative returns. Lumpsums have a longer left tail compared to DCA so probability of a large negative outcome is higher for the former.
However, the total area under zero is higher for DCA in MIDCAPs so the probability of negative outcomes in general is higher for DCA/SIP.
Lumpsums have a fat right tail for both MIDCAPs and GOLD so the probability of large positive outcomes is higher for lumpsums.
“Average” DCA returns are less than “average” lumpsum returns but they occur with a higher probability.

For a prudent investor, it is the left tail that matters the most. Even though lumpsums hold out hope for higher returns (fat right tails,) they have a small probability of a big loss that is greater than that for DCA (longer left tails.) In conclusion, a prudent investor should convert a windfall into an STP and a risk-seeker should do a lumpsum.

For readers curious about the code and for additional charts with longer time periods, visit github.
Benchmarking against a Momentum Index

When we first launched our momentum strategy in India back in 2013, we were one of the few to openly talk about momentum as a systematic strategy. Even the thematic indices that were later launched by the NSE focused on value and beta. This resulted in momentum strategies being forced to inappropriately benchmark against market-cap weighted indices. Thankfully, that is not the case anymore.

S&P BSE Momentum Index

The BSE came out with a Momentum Index last year which can now be used to benchmark momentum strategies. An obvious flaw in this index is that it is rebalanced only once in 6 months whereas most academic research on momentum assume a monthly rebalance. However, if you look past that, it is a better alternative.

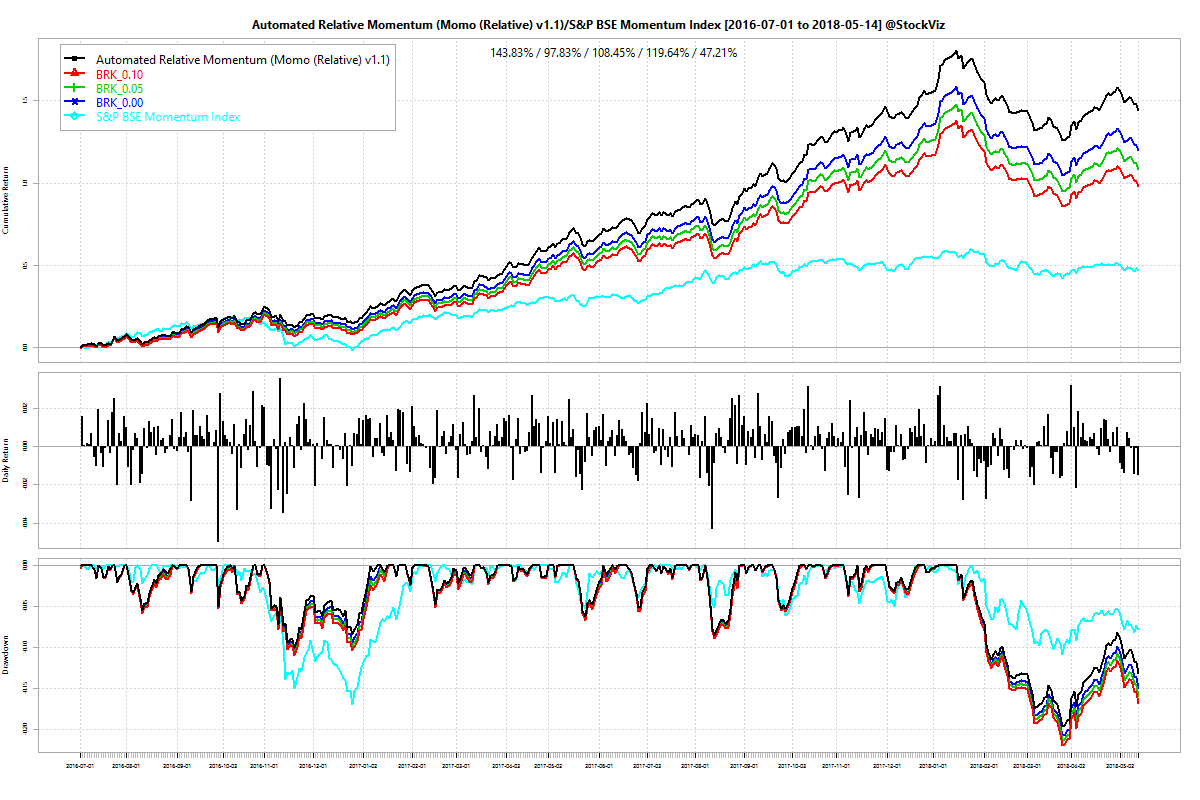
Here is how our Momo Relative Momentum strategy compares against the index:

Our risk-managed momentum strategy has out-performed the momentum index even after transaction costs.

Portfolio Management vs. Stock Selection

Retail investors and their media diet tend to focus too much on what stocks to buy and which IPOs to subscribe rather than portfolio construction and maintenance. Some of these aspects were touched upon here and here. Below are some portfolio level questions that investors should answer before they dive into stock selection:

  1. Is cash allowed? If enough number of stocks cannot be found to fit the investment thesis, or if the market is “bad,” is the portfolio allowed to hold cash? Remember that cash in the brokerage account earns zero.
  2. What is the maximum number of positions? How much time is to be spent everyday on surviellance?
  3. How much of each stock is to be purchased? Is it going to be equal-weight, cap-weight (free-float or full-float) or factor-weight?
  4. Will there be hard position and sector limits?
  5. How will IPO subscriptions where the target allocation is not filled be handled?
  6. What will be covered in daily surveillance? Things to consider: M&A, management, regulations, competitor profile, government interference, etc.
  7. How will costs be controlled? Direct investing is an extremely expensive proposition in India. What are net portfolio returns after: STT, brokerage, exchange fees, SEBI fees, stamp duty, GST/IGST, demat fees, demat transaction charges, short-term gains tax, long-term gains, etc?
  8. Will the portfolio be bench-marked? Should the appropriate benchmark be a basket of mutual funds that could have otherwise been invested into?
  9. What about risk management? Is it going to be a long-only balls-to-the-wall portfolio or are there going to be hedges, stop-losses, etc.?
  10. What is the re-balancing strategy? Will the whole portfolio be recomputed or will only those positions that strayed too far away from the thesis be looked at? How often will this exercise be undertaken?

Unless investors can think through these questions, stock selection is irrelevant.

Transaction Cost Analysis of a Momentum Strategy

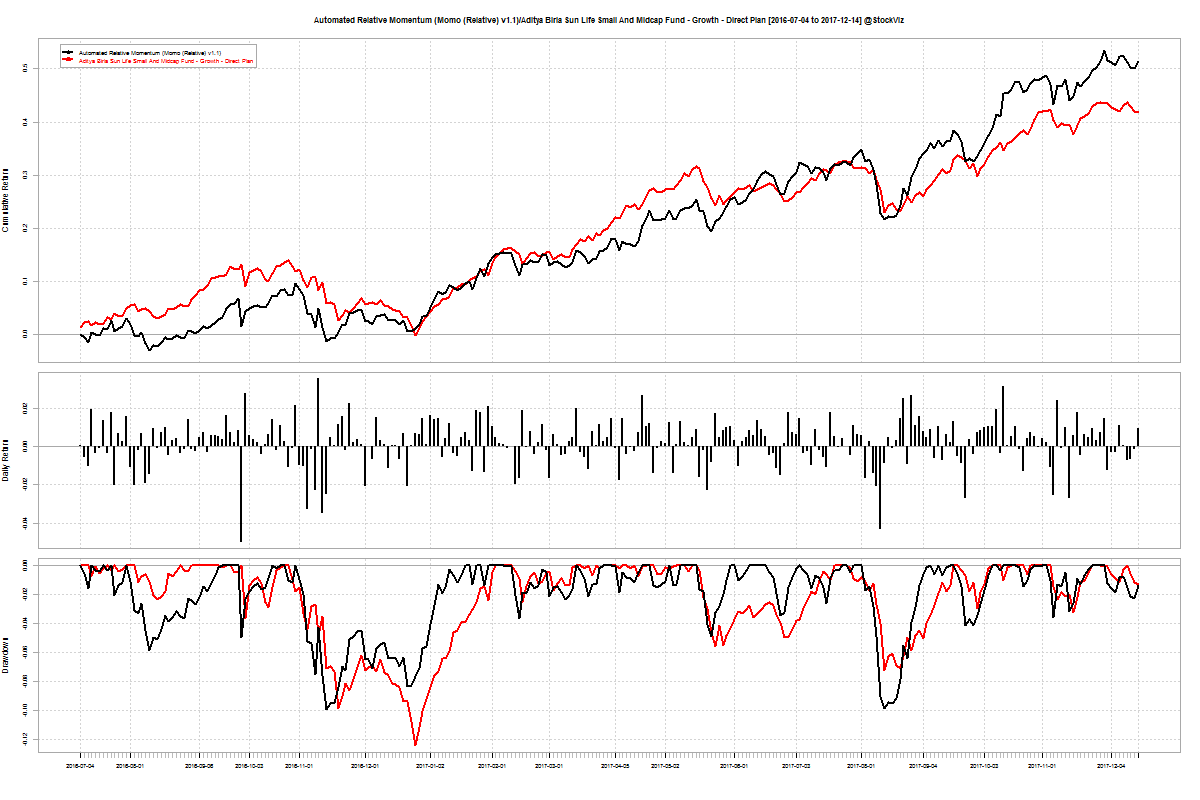
Momentum strategies have been on a tear over the last few years and have generally out-performed pure-value strategies. When we compare momentum returns with mutual funds, the most common criticism we encounter is that mutual fund returns are after transaction costs whereas our “Theme” returns are before transaction costs.

Momo (Relative) v1.1 vs ABSL S&M Fund (Annualized returns are 85.50% and 35.12%, respectively.)

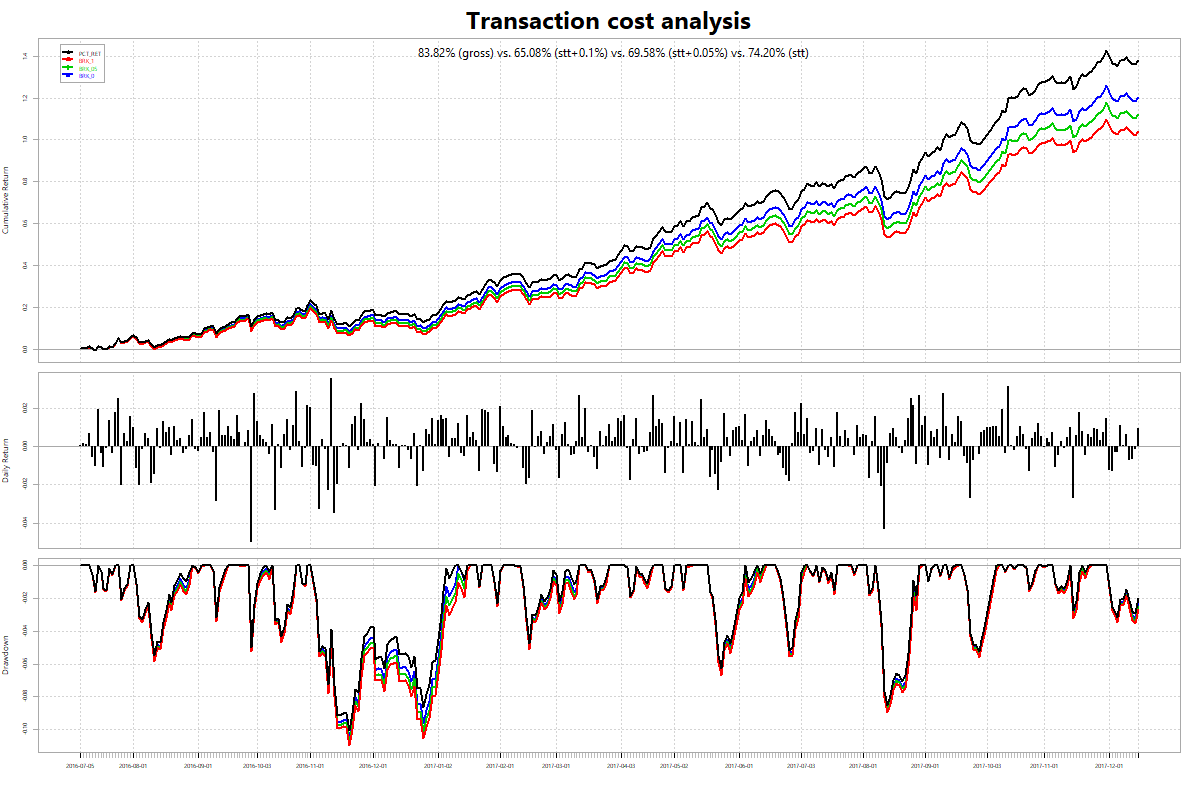
The challenge we face in showing post-cost returns is that we offer different brokerage slabs to different types of clients, making a one-cost-fits-all analysis impossible. However, we can show how different brokerage slabs impact returns.

A gross return of 83.82% translates to returns of 74.20%, 69.58% and 65.08% for brokerage slabs of 0.1%, 0.05% and 0% respectively (STT of 0.1% was assumed.) Momentum out-performs even after transactions costs.

An Equity, Bond and Gold Portfolio

How did diversification across Midcap equity, bonds and gold work out for Indian investors over the last 10 years? Not too shabby, as it turns out:

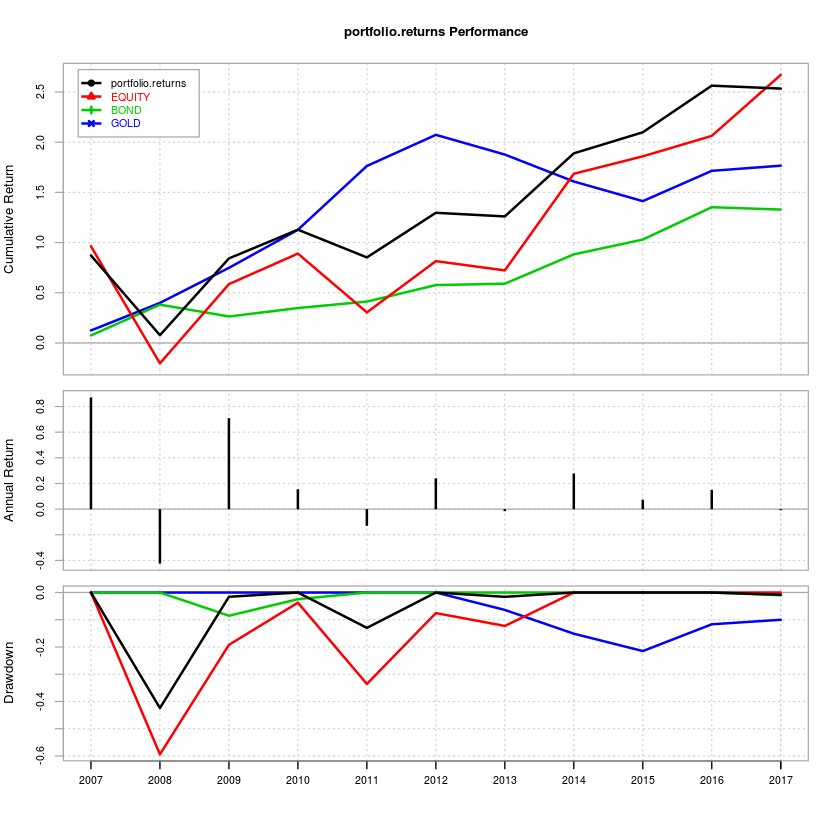
Combined portfolio – Annualized: 12.16%; Max drawdown: -42.42%
Gold only portfolio – Annualized: 9.69%; Max drawdown: -21.49%
Equity only portfolio – Annualized: 12.55%; Max drawdown: -59.39%
Bond only portfolio – Annualized: 7.99%; Max drawdown: -8.52%
*Not including transaction charges/taxes.

The Setup

  • Annual rebalance.
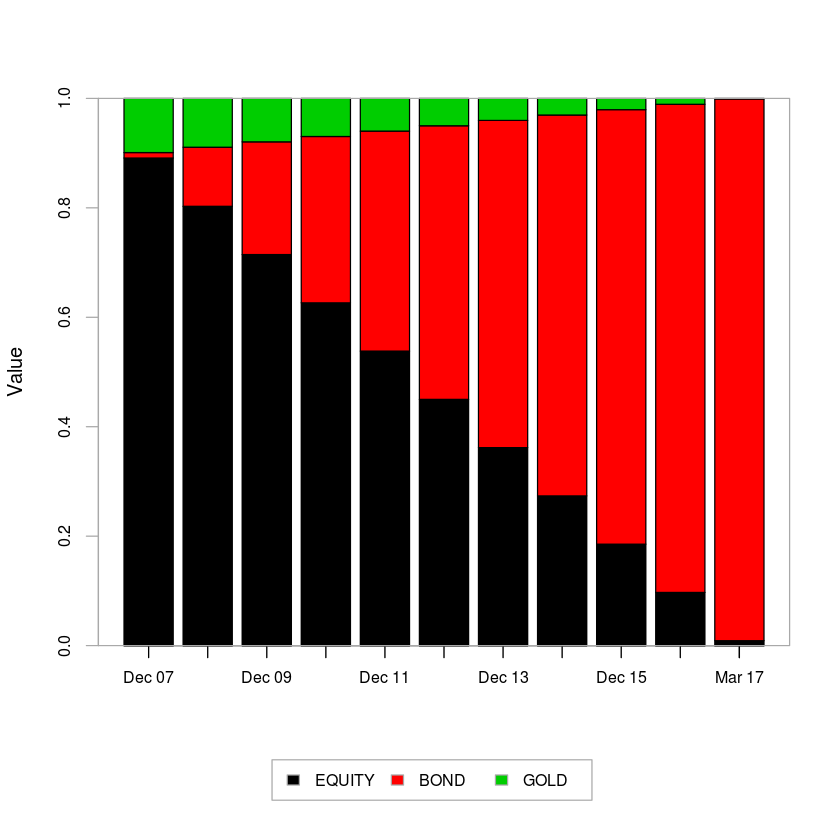
  • Bonds start at 1%, the rest is divided between Gold (10%) and Equities.
  • The total return index for the 5-10 year tenure published by CCIL is used as a proxy for Bonds.
  • The MID100 FREE index is used as a proxy for Equities.
  • The GOLDBEES ETF is used as a proxy for Gold.
  • Period under observation: 2007-04-01 through 2017-03-31.

The idea is that you start with mostly Equity and Gold in the portfolio and rebalance at the end of every year so that at the end of 10 years, you end up with mostly Bonds.

Returns

Notice the drawdown of the equity vs. that of the portfolio. You end up with similar returns but with lower volatility.

If you remove Gold from the equation and go with only Equity and Bonds:

Combined portfolio – Annualized: 11.38%; Max drawdown: -49.90%
Equity only portfolio – Annualized: 12.55%; Max drawdown: -59.39%
Bond only portfolio – Annualized: 7.99%; Max drawdown: -8.52%

Even though a diversified, rebalanced portfolio makes sense on the surface, the tax treatment on Gold and Bonds make an annual rebalance an expensive affair.

Code and detailed results are on Github.